Monthly cost
From
4 708 kr/mån*
excl. admin fee
- Current interest rate
- 6,95 %*
- APR
- 7,56 %
*The interest rate is variable, so the interest rate and the monthly cost may change during the term of the agreement, e.g. if the lender's borrowing costs change; for more information, see the agreement with the lender. The lender is entitled to keep the interest rate unchanged if the rate used to calculate the lender's borrowing costs is at or below 0%.
Representative example
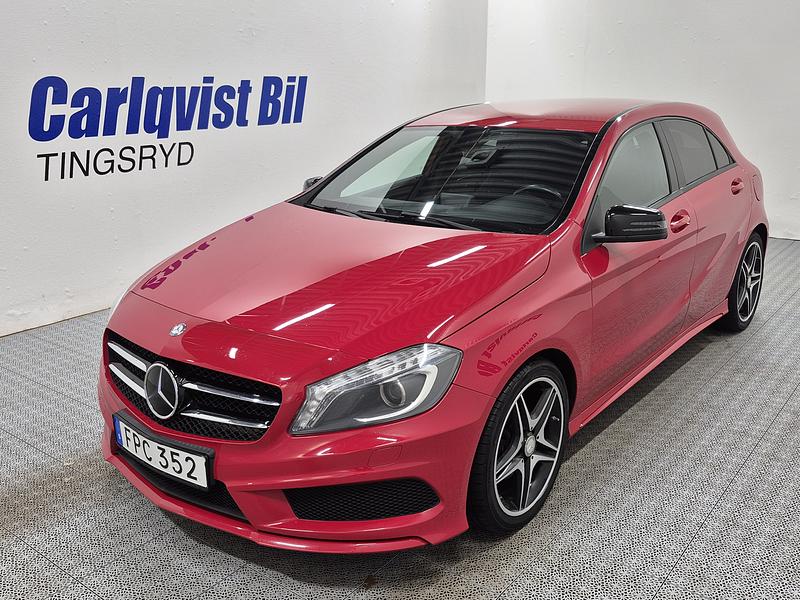
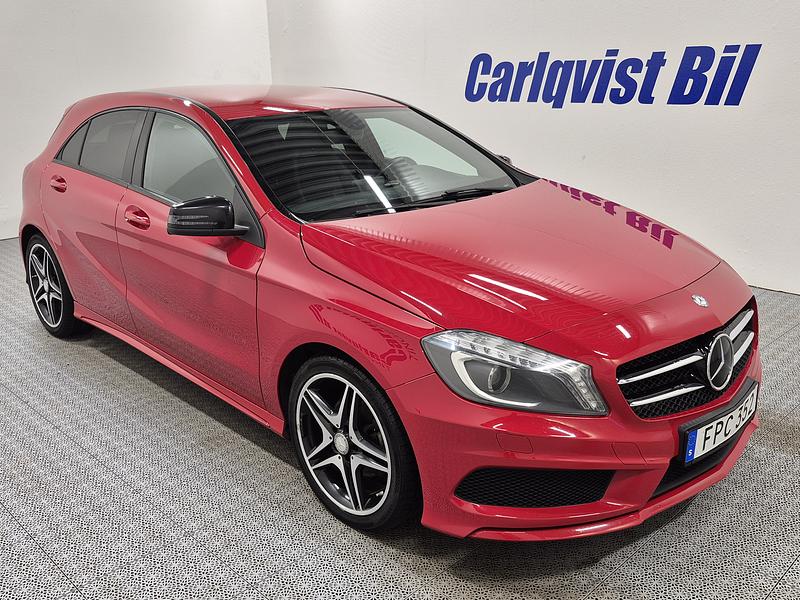
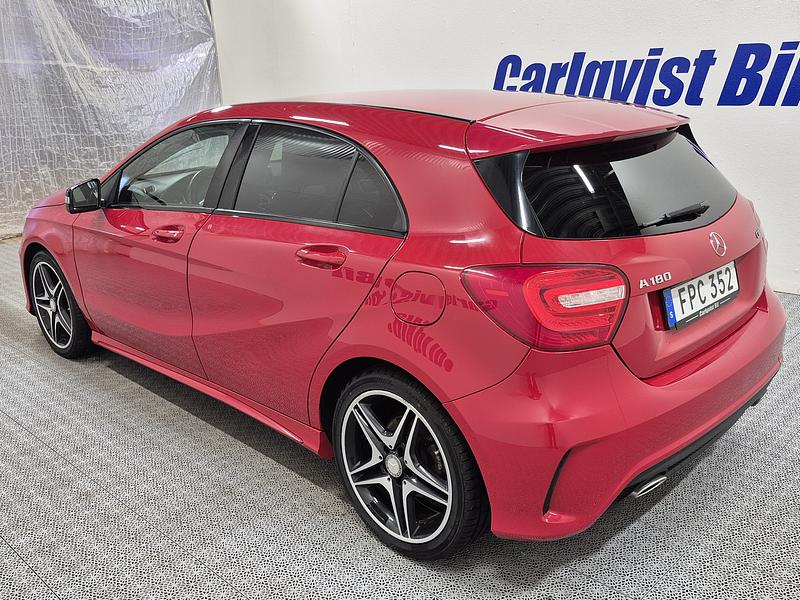
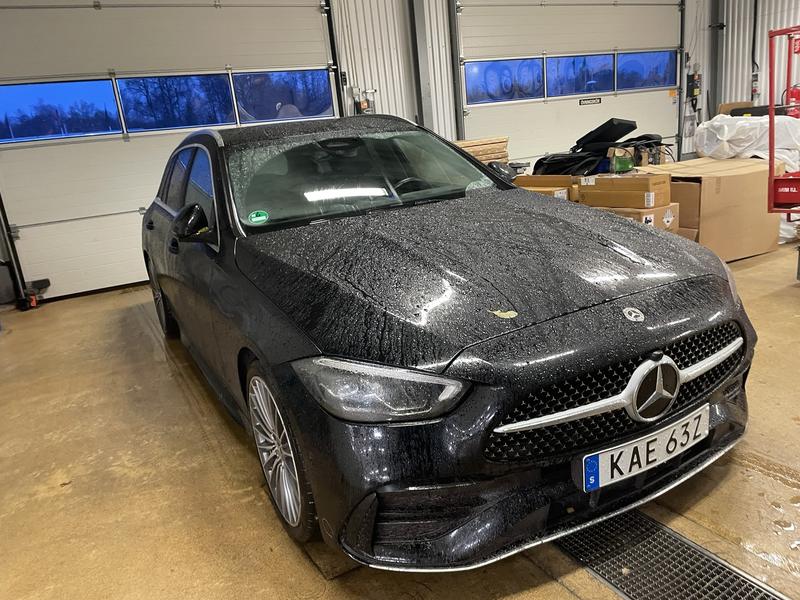
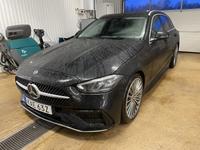
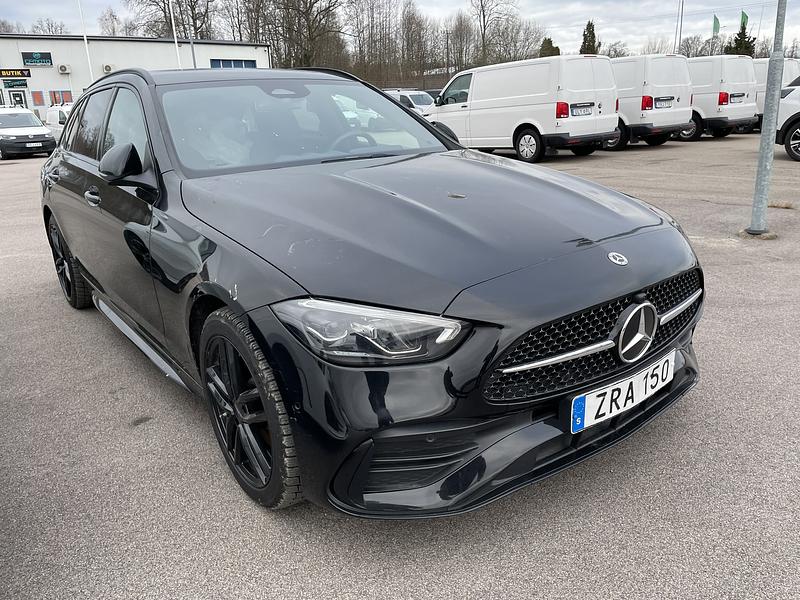
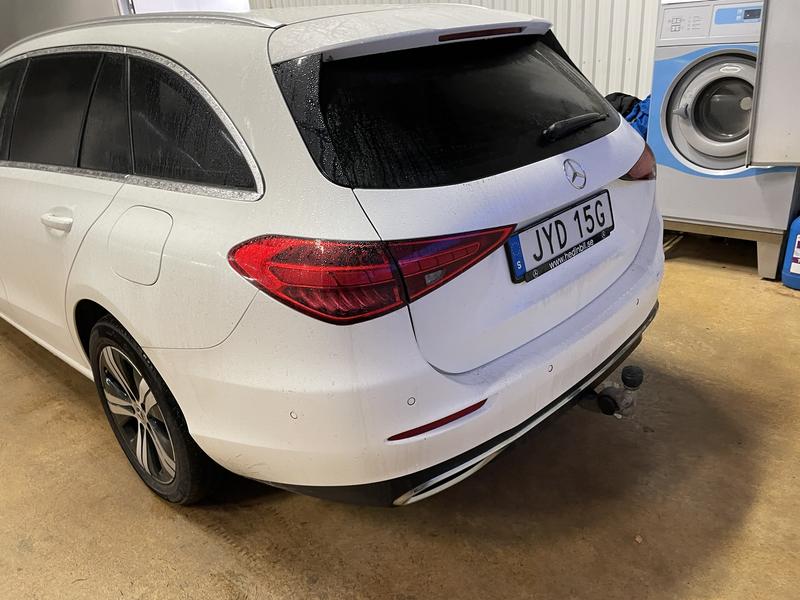
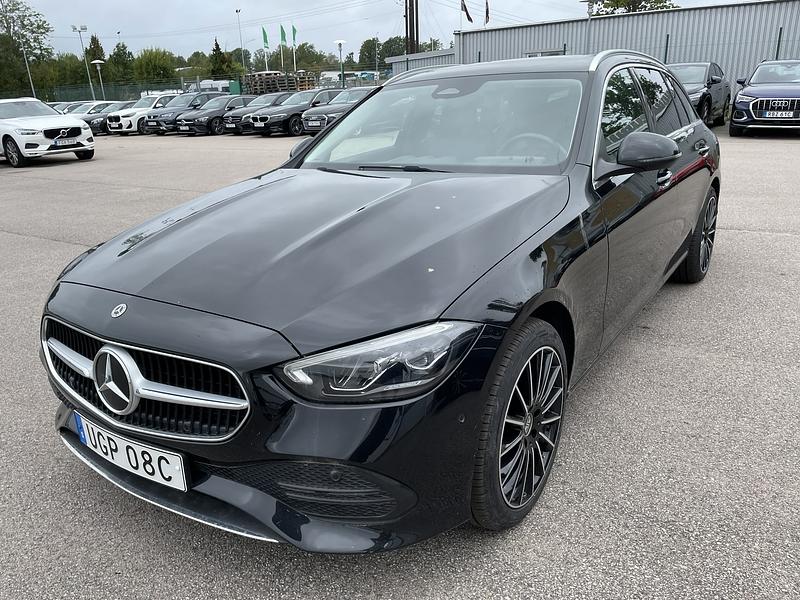
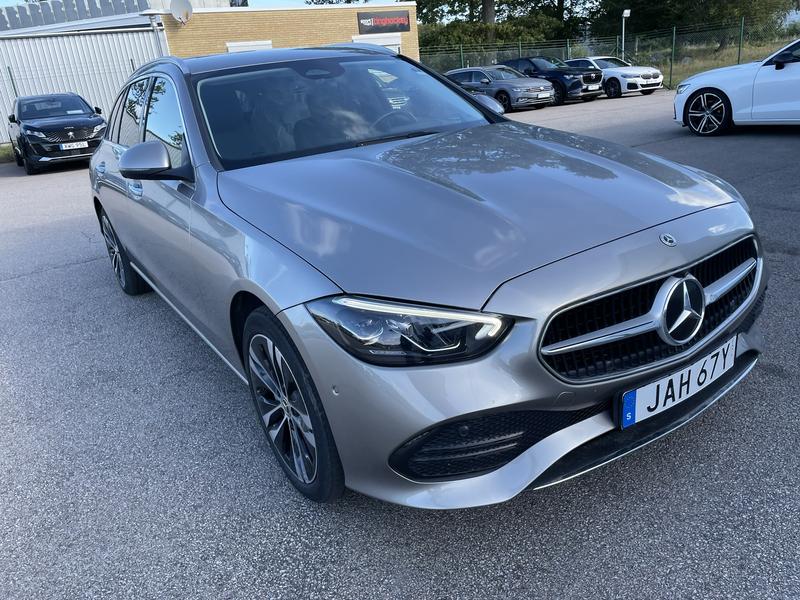
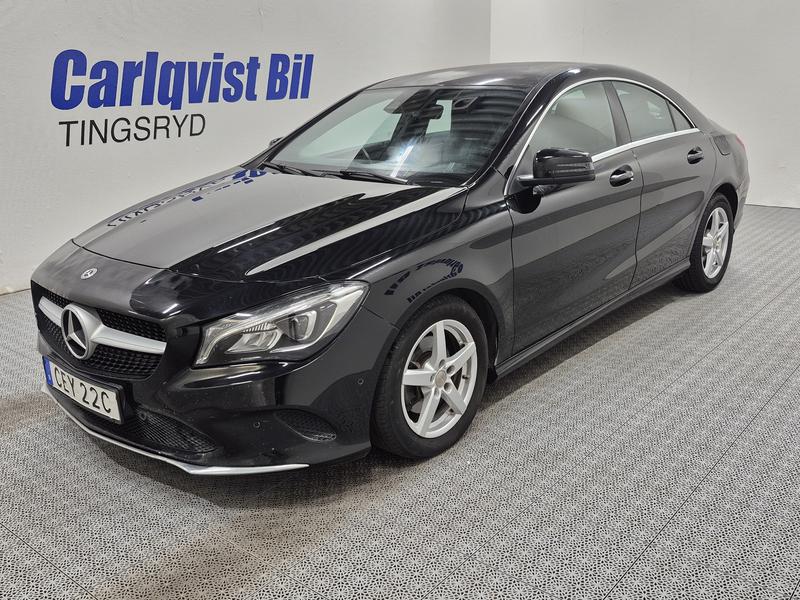
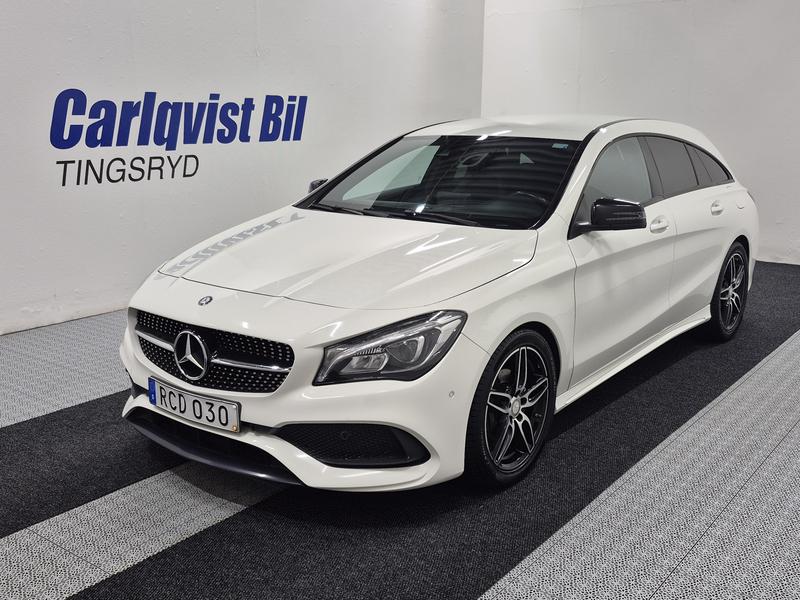
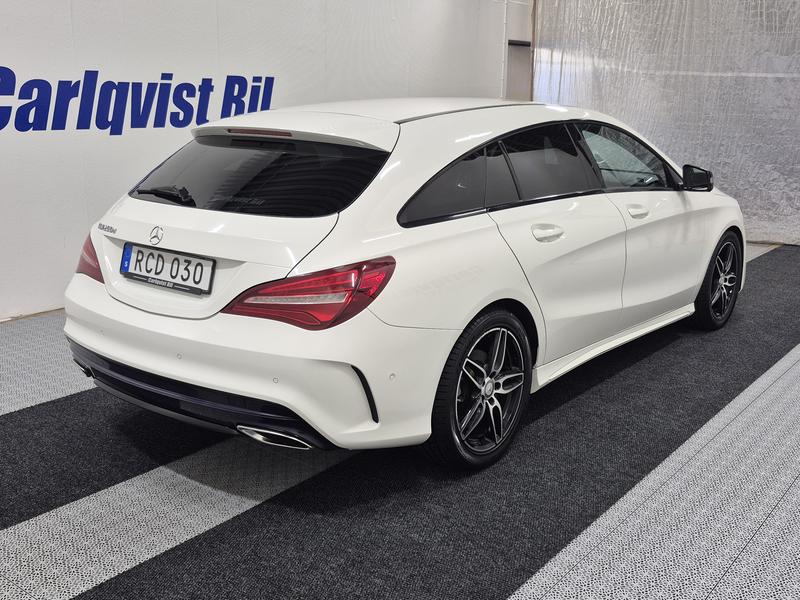
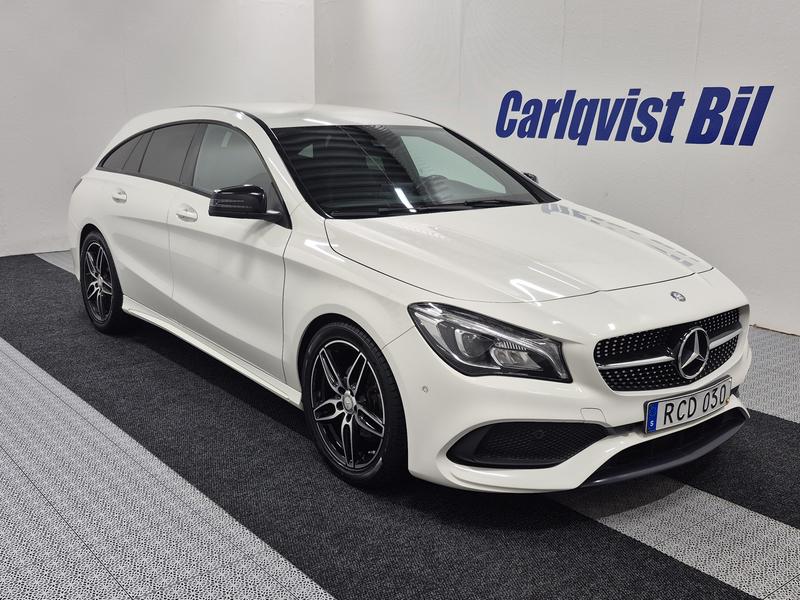
Price of the car 389 000 kr, deposit (20 %) 78 000 kr, credit amount (incl. residual debt) 311 000 kr, credit period 36 months and residual debt 195 000 kr (50 % of the car's price) at the end of the credit period. Variable interest rate currently 6,95 %*, arrangement fee 588 kr, administration fee 60 kr/month, gives an APR of 7,56 %. This gives a monthly cost of currently 4 708 kr/month* excl. admin fee (annuity loan with residual debt). At the end of the credit period, a residual debt of 195 000 kr remains. The total amount payable for the credit, including the residual debt, interest and fees, is 367 253 kr. The lender does not guarantee the car's value at the end of the credit period.
Subject to a standard credit check. Financing is offered through Carlqvist Bil in partnership with external lenders. The lender and finance terms are determined in connection with the credit application.
- Credit amount (incl. residual debt)
- 311 000 kr
- Total amount payable
- 367 253 kr
About instalment loans with residual debt
An instalment loan with a residual debt means that, as the borrower, you pay down the loan monthly during the credit period to a predetermined residual debt. At the end of the credit period you pay the remaining credit amount, the so-called residual debt. The total credit amount therefore includes the residual debt.
The residual debt usually corresponds to the car's estimated value** at the end of the credit period, but as the borrower you can always choose a lower residual debt in advance. The residual debt must be paid by the borrower regardless of the car's actual value at the end of the credit period. As the borrower, you therefore always bear the car's actual depreciation, just as when you buy a car for cash. The lender therefore does not guarantee the car's value at the end of the credit period.
If the credit period is extended, the interest rate and repayment rate applied by the lender at that time will apply – which may affect the monthly cost. This applies even if the interest rate was fixed during the ordinary credit period.
**Estimated depreciation for cars is calculated using established industry calculations based on historical depreciation, car model, equipment, mileage, etc. Many factors can affect a car's depreciation, and its market value can also be affected by unforeseen events.
Borrowing costs money!
If you cannot repay the debt on time, you risk a payment default. This can make it difficult to rent a home, take out subscriptions and get new loans. For support, contact the budget and debt counselling service in your municipality. Contact details are available at konsumentverket.se.